
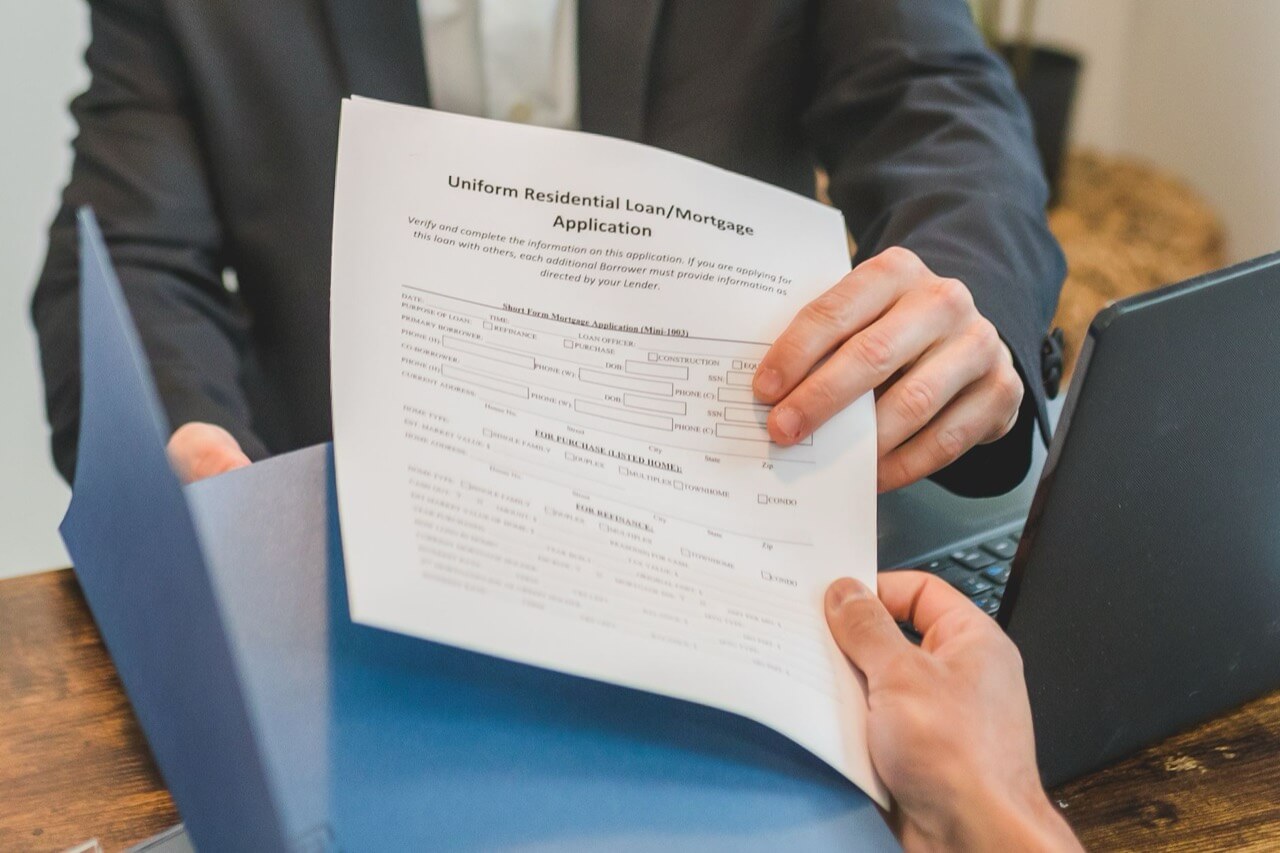
How a HELOC approval review works
A home equity line of credit (HELOC) is generally secured by your home. If you already have a first mortgage, the HELOC may be recorded behind it as a second lien. A lender can therefore review both your ability to manage payments and the property securing the debt.
The review may consider your credit history, existing obligations, documented income, available equity, property details, and title information. To assess equity, a lender may compare the property’s estimated value with the first mortgage balance and the requested HELOC limit. Combined loan-to-value (CLTV) reflects the total mortgage debt being measured against the property value; it may account for the full line limit, not just the amount you initially expect to draw.
There is no single credit-score or CLTV threshold that applies to every lender and program. Valuation methods, eligible properties, required documents, and repayment structures vary. A HELOC is generally a revolving line, while a home equity loan is typically a separate loan with its own terms. Approval is subject to credit approval and program guidelines.
Questions about your situation?
Talk it through with a loan officer who knows this market. No forms and no pressure.
Irvine home values put valuation in focus
Zillow Research reported an Irvine home value of $1,492,449 in August 2026. That market figure is useful context for a HELOC conversation, but it is not an estimate of your individual property or the equity a lender will approve.
Use property-specific evidence, not a citywide average
The Census ACS 5-Year reported a median home value of $915,500 for Orange County, California, in 2023, while Zillow Research reported Irvine’s home value at $1,492,449 in August 2026. These figures cover different geographies and vintages, so neither substitutes for a lender’s valuation of a particular Irvine home. For a HELOC, property condition, location, recorded liens, and the lender’s valuation method all affect how much equity may count.
Zillow Research reported that Irvine home values had changed by -1.82% year over year in August 2026. That movement makes it especially important not to base a requested line solely on an older estimate: the lender will assess the property under its own current process. When I review an Irvine HELOC file, I check the property details and compare the valuation assumptions with neighborhood-level evidence before flagging questions for the lender’s review; a local estimate is context, not an approval decision.
Timing and negotiation can affect the valuation picture
Zillow Research reported 40 days to pending in Irvine in August 2026. That market timing is context, not a promise about how quickly a HELOC valuation or approval will finish; a lender still needs to review the specific application and property.
Price reductions can also be relevant background when comparing a home with nearby sales. Zillow Research reported that 29.98% of Irvine listings had price cuts in August 2026. This does not determine an individual home’s value, but it is a reason to share accurate details about recent improvements or unusual features rather than assume an online estimate captures them.
Prepare for the payment and property-cost review
A HELOC review may include documented income, monthly debts, and the proposed payment structure, not only available equity. The Census ACS 5-Year reported a median property tax of $6,096 in Orange County, California, in 2023. Your own tax obligation may differ, but having current housing costs and mortgage information ready helps frame what payments you already manage alongside a proposed line.
Gather recent mortgage statements, debt information, income records, and property documents. If you are self-employed or have variable income, ask which records apply to your file. The lender’s requirements depend on the program and the details of your application.
How much equity can I use for a HELOC in Irvine?
There is no single amount that applies to every Irvine borrower. A lender generally compares the property’s accepted value with your existing mortgage balances and requested HELOC limit, then applies its own CLTV and eligibility guidelines. Zillow Research reported an Irvine home value of $1,492,449 in August 2026, but that citywide figure cannot establish the value or available equity of your home. Your mortgage balance, property-specific valuation, and lender’s rules determine the review.
Does a recent change in Irvine home values affect a HELOC application?
It can matter because a lender assesses available equity using its valuation process, rather than relying only on a past estimate. Zillow Research reported that Irvine home values changed by -1.82% year over year in August 2026. That market trend does not decide an individual application, but it reinforces the importance of current property information, mortgage balances, and the lender’s valuation of your specific home.
Part of this series
The numbers behind this page
Every figure comes from public data on Irvine, CA and Orange County. Each one names its source and the month it describes, so you can check it yourself.
